On September 19, 2026, Tesla, along with SpaceX and xAI, is embroiled in a trademark dispute over its Terafab chip factory, which has yet to produce any chips. The conflict began when Tera-Print, a nano-manufacturing equipment firm based in Illinois, issued a cease-and-desist letter in May, demanding that Tesla and SpaceX cease using the Terafab name. After unsuccessful negotiations on September 2, Tesla filed a lawsuit in Austin federal court, seeking a ruling that the Terafab name does not infringe on Tera-Print’s trademark rights. Tera-Print claims that Tesla proceeded with litigation while still expressing interest in negotiation and has vowed to vigorously defend its trademark rights. The case is currently pending in federal court in Austin.
SMCI’s Price-to-Sales (P/S) ratio is approximately 0.56, significantly below its historical median, indicating that earnings-based valuation methods like P/E do not apply due to the company’s cash flow negativity. SMCI has a GF Score™ of 85/100, suggesting strong overall performance relative to its peers. Insider activity shows a significant sell-off, with $15.44 million in insider sales over the last three months, raising concerns about confidence in the company’s future. What’s Behind the News?
The trademark conflict involving Tesla and its associated companies highlights the competitive and litigious environment in which technology firms operate. The Terafab chip factory is a critical component of Tesla’s strategy to enhance its technological capabilities, particularly in the rapidly evolving semiconductor market. The outcome of this legal battle could have implications not only for Tesla’s operations but also for its stock performance, as legal disputes can create uncertainty among investors.
Super Micro Computer Inc SMCI, a key player in the technology sector, specializes in high-performance server and storage solutions. With a market capitalization of approximately $25.68 billion, SMCI operates primarily in the hardware industry, providing products that cater to data centers, cloud service providers, and enterprises. The company has established a strong presence in the market, particularly in the United States, where it generates the majority of its revenue.
Is SMCI Overvalued on a Price-to-Sales Basis?
SMCI’s current Price-to-Sales (P/S) ratio stands at approximately 0.56, which is significantly lower than its historical median. This suggests that the market is pricing the company at a discount relative to its past performance and industry peers. Given that SMCI is currently unprofitable and cash-flow-negative, traditional earnings-based valuation metrics such as P/E are not applicable. The market appears to be pricing in a lack of confidence in the company’s ability to generate positive cash flow in the near term.
While the GF Value™ for SMCI is calculated at $84.10, indicating that the stock is undervalued by approximately 53.5% compared to its current price of $39.09, this figure should be viewed as a directional warning rather than a precise target due to the company’s ongoing losses. For more details, visit GF Value™.
What Does SMCI’s GF Score™ Tell Us?
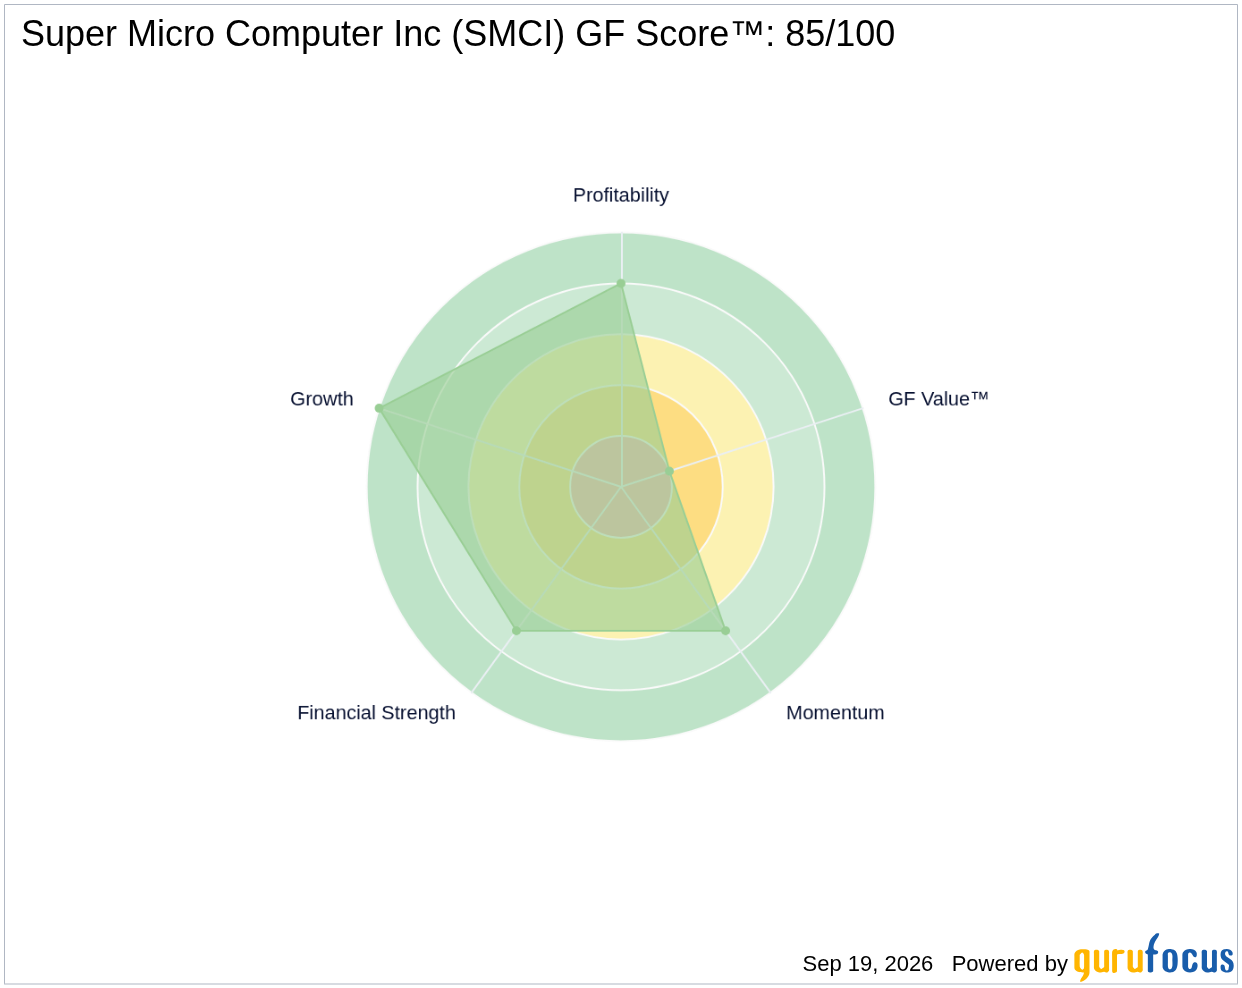
The GF Score™ is a comprehensive measure that evaluates a company’s financial strength, profitability, growth potential, valuation, and momentum. SMCI’s score of 85 indicates a strong performance, particularly in growth, where it ranks 10 out of 10. However, its valuation rank is concerning, at 2 out of 10, suggesting that the stock may be overvalued based on its current financials.
Metric Rating GF Score™ 85 Financial Strength 7 Profitability 8 Growth 10 Valuation 2 Momentum 7
SMCI’s strengths lie in its growth potential and profitability, while its valuation remains a significant concern. The low valuation rank indicates that investors should be cautious when considering this stock. For further insights, visit the SMCI stock page.
What Are Gurus and Insiders Doing with SMCI?
Currently, 8 gurus hold shares of SMCI, with 7 adding to their positions and 2 trimming their holdings in recent quarters. This indicates a generally positive sentiment among institutional investors. However, the insider activity shows a concerning trend, with $15.44 million in insider sales over the last three months, which may signal a lack of confidence in the company’s future performance.
What This Means for Investors
In summary, while SMCI presents a strong growth profile and a solid GF Score™, the significant insider selling and low Price-to-Sales ratio raise red flags about its valuation and future profitability. Investors should approach this stock with caution, considering the potential for a value trap. For more detailed analysis, check out the SMCI stock page.
Frequently Asked Questions
What is SMCI’s GF Score™?
SMCI has a GF Score™ of 85, indicating strong overall performance relative to its peers.
Is SMCI overvalued or undervalued?
SMCI is currently undervalued based on its Price-to-Sales ratio, but traditional P/E metrics are not meaningful due to the company’s cash flow negativity.
What is SMCI’s P/E ratio compared to historical?
SMCI’s trailing P/E ratio is 11.89, significantly lower than its 5-year median of 19.34, reflecting the company’s current struggles with profitability.
This stock alert was generated using automated technology and GuruFocus financial data to provide readers with timely and accurate market reporting. This content was reviewed by GuruFocus editorial team prior to publication. Please send any questions or comments about this story to [email protected].